Cards
Issuers of service cards, non-bank credit, prepaid cards, vouchers and e-wallets.
Track both Section II threshold regimes on a single platform: service and non-bank credit cards (805 and 1,285 UMA) plus prepaid cards, vouchers, coupons and e-wallets (645 UMA), with API ingestion and XSD-validated XML reports.
- Legal basis
- Art. 17, section II
- Identification threshold
- 805 UMA ($94,435 MXN) credit · 645 UMA ($75,665 MXN) prepaid/vouchers
- Reporting threshold
- 1,285 UMA ($150,743 MXN) credit · 645 UMA ($75,665 MXN) prepaid/vouchers
- Multi-product rule (Sect. II)
- 2 simultaneous product thresholds
INTERACTIVE REGULATORY COCKPIT
Simulate AML Compliance for Your Industry
Calculated in real-time with official 2026 UMA ($117.31 MXN), Art. 17 notification thresholds and Art. 32 cash restrictions.
Art. 17 LFPIORPI
Identification on all operations; SAT XML report at 8,025 UMA and strict Art. 32 cash cap.
8,025 UMA ($941,412 MXN)
Identification threshold: Always (every deed/contract)
8,025 UMA ($941,412 MXN)
Exceeding this limit in cash constitutes a serious sanction under Art. 53.
Anexo 5
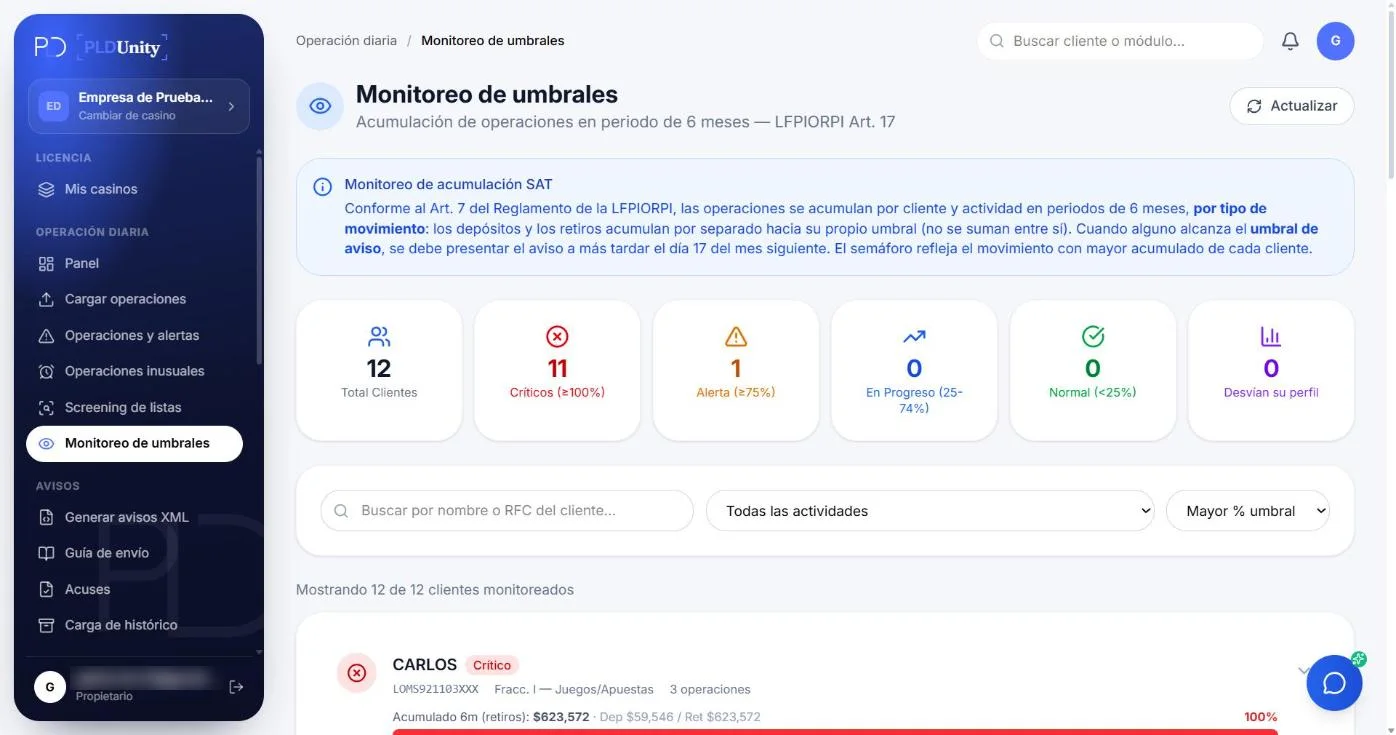
Cumulative 6-month threshold monitoring per client
CAPABILITIES FOR YOUR INDUSTRY
How PLDUnity helps
- 01Feature
Dual product thresholds in one account (Section II)
Configure and separate service/credit cards (ID 805 UMA / Report 1,285 UMA) and prepaid/vouchers/e-wallets (ID and Report from 645 UMA) under the same company.
- 02Feature
6-month accumulation per cardholder or corporate buyer
Sums loads, top-ups, payments and spending per cardholder or corporate client over rolling 6-month windows using the UMA in force on each transaction date.
- 03Feature
Digital KYC onboarding for individuals and companies
Collect KYC files via remote link with AI extraction of IDs, corporate deeds, powers of attorney, tax certificates and Beneficial Owners without slowing card issuance.
- 04Feature
REST API integration or AI-assisted file upload
Connect your card processor via REST API with idempotency keys or upload monthly files and let AI map your custom columns automatically.
- 05Feature
Automated 8-source screening & 24-hour unusual cases
Screen cardholders and corporate buyers individually or in batches against SAT 69-B, OFAC, UN, PEP, FBI and OFSI, opening a 24-hour case on critical matches.
- 06Feature
Validated XML generation for Section II sub-schemas
Download the XML validated against the exact SAT XSD schema for service/credit cards, prepaid cards or vouchers before the 17th and retain acknowledgments for 10 years.
END-TO-END WORKFLOW
How PLDUnity runs end-to-end in your industry
A single connected workflow for issuances, loads, top-ups, spending and repayments—without re-keying data between spreadsheets and separate tools.
- 01KYC & Beneficial Owner
Identify every cardholder or corporate client
Onboard the cardholder or corporate buyer via a digital KYC link: AI-powered extraction of IDs, incorporation deeds, tax certificates and Beneficial Owner records.
- 02UMA & Art. 32 Engine
Capture, aggregate & check cash caps
Connect your card processor or core via API or monthly file uploads. PLDUnity automatically separates credit/service products (805 / 1,285 UMA) from prepaid/vouchers/wallets (645 UMA).
- 037 List Sources + EBR 2027
Watchlist screening & EBR risk grade
Run per-client or batch screening of cardholders and legal representatives against 7 watchlist sources and compute EBR risk scores based on top-up frequency, velocity and client profile.
- 04SAT XSD + 10-Yr Vault
Validated XML report & SHA-256 evidence
Generate the official Section II XML for each sub-product, validated against the SAT XSD before the 17th, with linked acknowledgments and full audit logs.
MEASURABLE IMPACT
Tangible value for every area of your company
PLDUnity removes friction from commercial operations while giving your Compliance Officer and Board verifiable certainty.
Digital issuance without slowing card placement
Corporate clients and cardholders upload documents through a single link during onboarding, eliminating email chains and rejected scans.
From days of spreadsheet work to minutes before the 17th
No need for separate systems for non-bank credit cards and prepaid vouchers or e-wallets: each product enforces its exact UMA threshold.
Protection against fines up to 65,000 UMA ($7.6M MXN)
Scale your fintech or card issuer transaction volume via API with signed webhooks and strict tenant isolation on Google Cloud.
WHY CHOOSE PLDUNITY
The PLDUnity differentiator
Built in Mexico by BDUnity®, an AML compliance consultancy advising reporting entities since 2012.
Tailored to your exact Article 17 fraction
We natively support the distinct Section II sub-schemas (service/credit cards, prepaid cards and vouchers/wallets) under a single company account.
Software with real consultants behind it
Created by BDUnity® (active since 2012). Every validation rule, annex checklist and audit package reflects real SAT inspections—not generic template software.
AI that accelerates, an Officer who decides
AI reads IDs, tax certificates and custom Excel columns in seconds, but every critical match, risk methodology and XML filing is confirmed by your Compliance Officer.
Google Cloud isolation & SHA-256 fingerprints
Each company runs isolated with TOTP 2FA, role-based segregation of duties, a server-only audit log and SHA-256 hashes on every XML, acknowledgment and 10-year export.
BEFORE & AFTER
Manual spreadsheets vs. PLDUnity in your industry
Why reporting entities replace disconnected folders and generic tools with a purpose-built LFPIORPI platform.
| Compliance dimension | Spreadsheets & disconnected tools | With PLDUnity® in your industry |
|---|---|---|
| 6-month UMA aggregation & thresholds | Mixing prepaid card top-ups (645 UMA threshold) with service card billing (1,285 UMA threshold) in the same spreadsheet. | Native sub-product separation within the same company, automatically enforcing 645 UMA for prepaid/vouchers and 805/1,285 UMA for credit/service. |
| Client KYC & watchlist screening | Small recurring top-ups over six months crossing the threshold without the core system triggering a KYC file request. | Rolling 6-month accumulation per cardholder that alerts your team before crossing the identification threshold. |
| Monthly SAT XML preparation | Manual XML capture prone to schema errors, malformed RFCs/CURPs and last-minute rejections on the 17th. | Pre-validated against the official SAT XSD schema for your activity, plus one-click nil reports and linked acknowledgments. |
| 2027 Risk-Based Assessment (EBR) | Static Word document without individual client risk recalculation or historical audit trail. | Four-factor EBR engine with capped mitigants that recalculates every client's risk grade on the 2nd of each month. |
| SAT / UIF inspection readiness | Weeks spent gathering scattered PDFs, emails and acknowledgments across former employees' computers. | One-click audit package with server-written logs, SHA-256 integrity hashes and expiring read-only access for external auditors. |
ALL-IN-ONE PLATFORM
All 8 platform modules working together for Cards
Your subscription includes the complete AML compliance suite—no hidden add-ons per module.
Transaction Upload (Excel, AI & API)
Validate every record against SAT catalogs with idempotency and 6-month accumulation.
UMA Threshold Monitoring
Automatic tracking of identification, reporting and Art. 32 cash caps in current UMA.
Digital Customer Files & Remote KYC
Remote link or QR with AI document reading (OCR), AI-assisted face match, and liveness test.
7-Source Watchlist Screening
UN, OFAC (SDN & consolidated), UK (OFSI), FBI, SAT 69-B, Non-Located & PEP queried per client, in batches, or manually.
2027 Risk-Based Assessment (EBR)
Four-factor risk methodology and per-client risk grade recalculated every month.
24-Hour Unusual Transactions
Automated case clock, red-flag analysis and documented Compliance Officer decisions.
SAT XML Generator (19 XSDs)
Pre-validated XML for your exact Article 17 fraction, one-click nil reports and acknowledgments.
10-Year SHA-256 Audit & Training
Immutable server log, 16-obligation self-assessment, AML courses and portable audit packages.
REGULATORY & OPERATIONAL GUIDE
Compliance Guidelines for Cards
Essential LFPIORPI obligations, identification criteria, and supervisory rules applicable to this activity.
AML compliance for non-bank card issuers, fintechs and voucher programs
Section II of Article 17 covers distinct products under one statutory umbrella: non-bank service and credit cards on one side, and prepaid cards, payroll/fuel vouchers, coupons and electronic wallets on the other. Each sub-product carries its own UMA thresholds (805 and 1,285 UMA for credit/service; 645 UMA for prepaid, vouchers and e-wallets) and its own SAT XSD schema.
At scale, the primary compliance risk comes from recurring top-ups or spending over a 6-month period crossing the threshold before a complete KYC file and Beneficial Owner record have been collected.
One connected platform for every Section II card product
PLDUnity lets you configure each product line with its exact threshold inside a single account. As transactions or top-ups arrive—via API or file upload—the engine updates each cardholder's running total, triggers early alerts before crossing the identification threshold and runs per-client and batch watchlist screening across 7 official watchlist sources.
FREQUENTLY ASKED QUESTIONS
Frequently asked questions
Do recurring top-ups on a prepaid card or e-wallet count toward the threshold?
Yes. All loads and top-ups over the period are accumulated per cardholder or corporate buyer; reaching 645 UMA ($75,664.95 MXN at 2026 UMA) triggers both identification and reporting.
Do we need two accounts if we issue both credit cards and prepaid cards or vouchers?
No. You configure each Section II sub-product with its own threshold (805/1,285 UMA and 645 UMA) inside the same company and generate the corresponding SAT XML.
How do we onboard corporate clients purchasing vouchers or fleet cards?
Collect the corporate buyer's legal entity file (incorporation deed, powers of attorney, tax certificate and Beneficial Owner) via a digital KYC link while aggregating total loads.
Can we stream transactions automatically from our card processor?
Yes. Pro and Enterprise plans include a REST API with idempotency controls and HMAC-SHA256 signed webhooks for zero-touch ingestion.
What are the exact 2026 MXN amounts (UMA $117.31) for credit/service cards and prepaid instruments?
For non-bank service and credit cards (Section II.a), identification starts at 805 UMA ($94,434.55 MXN) and monthly XML reporting starts at 1,285 UMA ($150,743.35 MXN) in monthly spending. For prepaid cards, vouchers, and wallets (Section II.b/c), both identification and reporting apply at 645 UMA ($75,664.95 MXN) per issuance or reload.
How does the platform detect unusual activity such as structured reloads or atypical wallet disbursements?
The Unusual Transactions module flags structuring patterns (multiple reloads just below 645 UMA), cash funding across different locations, and deviations from the cardholder's or corporate sponsor's EBR profile—enabling urgent 24-hour notices when warranted.
What do we file in months when no cardholder exceeds the 1,285 or 645 UMA notice threshold?
You must still submit a monthly Zero-Activity Report (Article 25 RCG) by the 17th of the following month. PLDUnity generates this filing in one click and archives the SAT receipt for 10 years.
30-DAY FREE TRIAL · NO CREDIT CARD
Ready to automate AML compliance for Cards?
Start your 30-day free trial with your own transactions or schedule a 30-minute walkthrough with BDUnity's compliance specialists.